Insurance for Restaurants in California
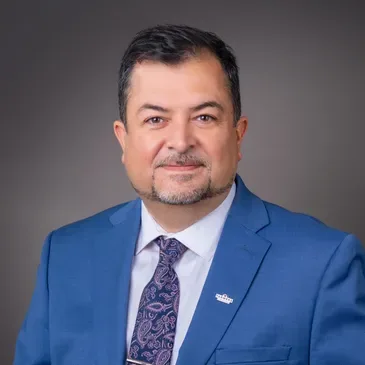
Your agent: Javier Calvo
- Licensed California agent — CA License #0L69621
- Hablamos español / Bilingual service
- Local office in Murrieta, CA
Restaurants run on thin margins and constant motion. Hot equipment, sharp tools, wet floors, customers coming and going, spoiled inventory after a power outage, a delivery driver in a fender bender. Any one of these can turn into a bill that lands on the owner.
We insure California restaurants, cafés, taquerías and food service businesses with three coverages: Business Owners Policy, Workers' Compensation and Commercial Auto. We'll explain what fits your kitchen, your staff and your vehicles — in English or Spanish, with no obligation.
How our three coverages fit
Business Owners Policy
A Business Owners Policy can help cover your kitchen equipment, inventory, furniture and tenant improvements, plus liability if a customer is injured — and lost income while you're closed after a covered loss, depending on the policy.
See coverageWorkers' Compensation
Kitchens see burns, cuts and slips routinely. California generally requires workers' comp for businesses with employees, and it can help cover medical care and lost wages when a cook or server is hurt at work.
See coverageCommercial Auto Insurance
If you run deliveries, catering vans or a food truck, commercial auto can help cover your vehicles and drivers — personal policies often exclude business use.
See coverage
Common questions
- I lease my restaurant space — do I still need insurance?
- Yes. Most California landlords require it, and the landlord's policy covers the building — not your equipment, inventory, improvements or your liability to customers.
- Does a Business Owners Policy cover spoiled food?
- Spoilage and equipment breakdown can be covered depending on the policy and endorsements. Tell us about your kitchen setup and we'll check what fits.
- Do I need workers' comp for part-time kitchen staff?
- California generally requires workers' compensation from your first employee, part-time included. We'll confirm how it applies to your staffing.
- What if my employees use their own cars for deliveries?
- That's a hired and non-owned auto situation — often an add-on to a commercial auto policy. If your staff deliver in personal vehicles, it's worth asking about.
Ready to see your number?
Start the quiz below. About a minute. No obligation.
Get a quote
Step 1 of 5Takes about 60 seconds — no obligation.
10 years serving California businesses, bilingual service, no obligation.