Insurance for Contractors in California
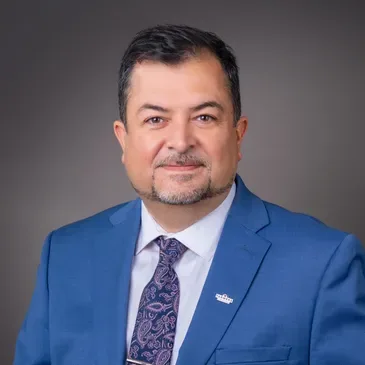
Your agent: Javier Calvo
- Licensed California agent — CA License #0L69621
- Hablamos español / Bilingual service
- Local office in Murrieta, CA
Contracting is physical work with real exposure on every job. A crew member gets hurt on a ladder. A customer's property is damaged mid-project. A loaded work truck is in a freeway accident. General contractors and clients also ask for certificates of insurance before you can start, so the right coverage is often what stands between you and the job.
We work with California contractors and construction trades every day. We write three coverages — Business Owners Policy, Workers' Compensation and Commercial Auto — and we can quote them together so your certificates, payroll class codes and vehicles are all handled in one place, in English or Spanish.
How our three coverages fit
Business Owners Policy
A Business Owners Policy can help cover your tools, equipment and office property, plus general liability if your work damages a client's property or someone is hurt — depending on the policy.
See coverageWorkers' Compensation
California generally requires workers' comp for businesses with employees, and construction is one of the most closely watched industries. It can help cover medical care and lost wages when a crew member is hurt on the job.
See coverageCommercial Auto Insurance
Work trucks and vans carrying tools and materials usually need commercial auto — personal policies often exclude business use. It can help cover liability and damage to your vehicles, depending on the policy.
See coverage
Insurance by trade
Plumbing Contractors
Plumbing work involves complex systems, potential water damage and interactions with many different clients, from residential repairs to commercial installations. The general liability in a Business Owners Policy can protect you if a client slips on a wet floor during a job, or if you accidentally cause water damage to a building — whether it's a client's home or a major leak at a commercial property — depending on the policy.
Your tools and equipment are the lifeblood of a plumbing business, and they're vulnerable to theft, loss or damage. Take an inventory to determine their total value, so the coverage you choose matches what you'd actually have to replace:
- Hand tools — wrenches, pliers, pipe cutters: replacement cost and how often you use them
- Power tools — drills, pipe threaders, camera systems: their value and maintenance costs
- Vehicles — work vans and trucks: age, mileage and any specialized modifications, for your Commercial Auto policy
- Safety equipment — hard hats, gloves, respirators: compliance requirements and how often they need replacing
Accidents can happen whether you're fixing a burst pipe in a customer's home or installing new plumbing in a retail space. Plumbers face real physical risks on the job, which is why Workers' Compensation matters so much for a plumbing crew.
Licensed California contractors generally must carry a contractor license bond required by the Contractors State License Board (CSLB) — currently $25,000 — and some construction projects call for additional bonds. Review your insurance policies regularly as your work changes, and adjust your deductibles to balance cost and protection.
Questions about this trade
- Are subcontractors covered under my plumbing business insurance?
- It depends on your policy terms. Generally, policies don't automatically cover subcontractors, so review your policy with us and consider additional coverage to protect your business from liabilities related to subcontractor work.
- How can I lower workers' comp rates for my plumbing company?
- Your claims history affects your premium, so workplace safety is the part you control. Implement safety training, provide proper protective equipment, keep a clean work environment, review and update your safety protocols regularly, and promptly address any hazards or incidents. Over time, fewer claims can help keep your rates down.
HVAC Contractors
HVAC work involves complex systems, electrical components and potential hazards. Your work often involves both electrical and mechanical systems, which increases the potential for property damage — and when things go wrong, the damage can be significant. Faulty installations, equipment malfunctions and injuries on the job site are the risks HVAC contractors need to plan for.
That exposure extends beyond your own tools and vehicles to clients' homes and businesses during installations or repairs. The general liability in a Business Owners Policy can help with damage to a client's property caused by accidents, negligence or equipment malfunctions, depending on the policy.
Your HVAC company likely owns specialized tools and machinery that require precise valuation. Keep an up-to-date inventory of all your equipment, including purchase dates, costs and current market values, so your coverage keeps pace with what you own — and ask us how equipment is covered while it's being transported between job sites.
Factor in the risks of subcontractors and employees working on various job sites, including roof-related accidents, and review your policies as your payroll and operations grow.
Questions about this trade
- How much liability coverage does an HVAC business typically need?
- Many HVAC businesses carry $1 million to $2 million in general liability, and $1 million per occurrence is a common client and contract requirement. The right amount varies with company size, services offered and location, and some clients or contracts require higher limits — tell us what your contracts ask for and we'll match it.
Electrical Contractors
Electrical work takes you into homes, office buildings and retail spaces, manufacturing facilities, and construction sites during new builds or renovations. In any of them, an accident during the work can damage someone's property or hurt someone.
Property damage caused by faulty wiring, electrical errors or an improper installation is generally a general liability matter — part of a Business Owners Policy — depending on the policy.
Professional mistakes can also put an electrician's license at risk. Claims of negligence or errors in your work, such as allegations of code violations or financial losses from project delays, may fall outside general liability. Contractors' errors and omissions (E&O) insurance is written for those claims, on both ongoing and completed projects.
Electrical tools and equipment are expensive. Tool and equipment coverage, often called inland marine, can protect against theft and damage on job sites and during transportation, can include replacement cost for stolen or damaged items, and can extend to rented or leased equipment, depending on the policy.
Tell us what your contracts and clients require — contact us and we'll talk through how our coverages fit your work.
Common questions
- Do California contractors need workers' comp?
- California generally requires workers' compensation for any business with employees, and the rules are especially strict in construction. Tell us how your crews are set up and we'll walk you through it.
- Can you provide certificates of insurance for my clients?
- Yes. Once your policies are in place we can issue certificates showing your coverage to general contractors and clients who ask for them.
- Are my tools covered in my truck?
- Tools and equipment in a vehicle can be covered depending on how the policy is written. It's one of the first things we review, because for many contractors the tools are worth more than the truck.
- Can I get a quote in Spanish?
- Absolutely. Our agency is fully bilingual — your quote, your paperwork and your questions are handled in English or Spanish, whichever you prefer.
Ready to see your number?
Start the quiz below. About a minute. No obligation.
Get a quote
Step 1 of 5Takes about 60 seconds — no obligation.
What do you need covered?
10 years serving California businesses, bilingual service, no obligation.